August Inflation Rose to 4.0%: Keep Housing Bills Separate
ABS annual CPI rose to 4.0% in August 2026, with housing up 5.7%. Read the figures and a worked budget example without treating inflation as a personal bill forecast.
Try the Inflation Calculator Australia
Run the numbers while you read and see how the concepts apply to your situation.
What changed
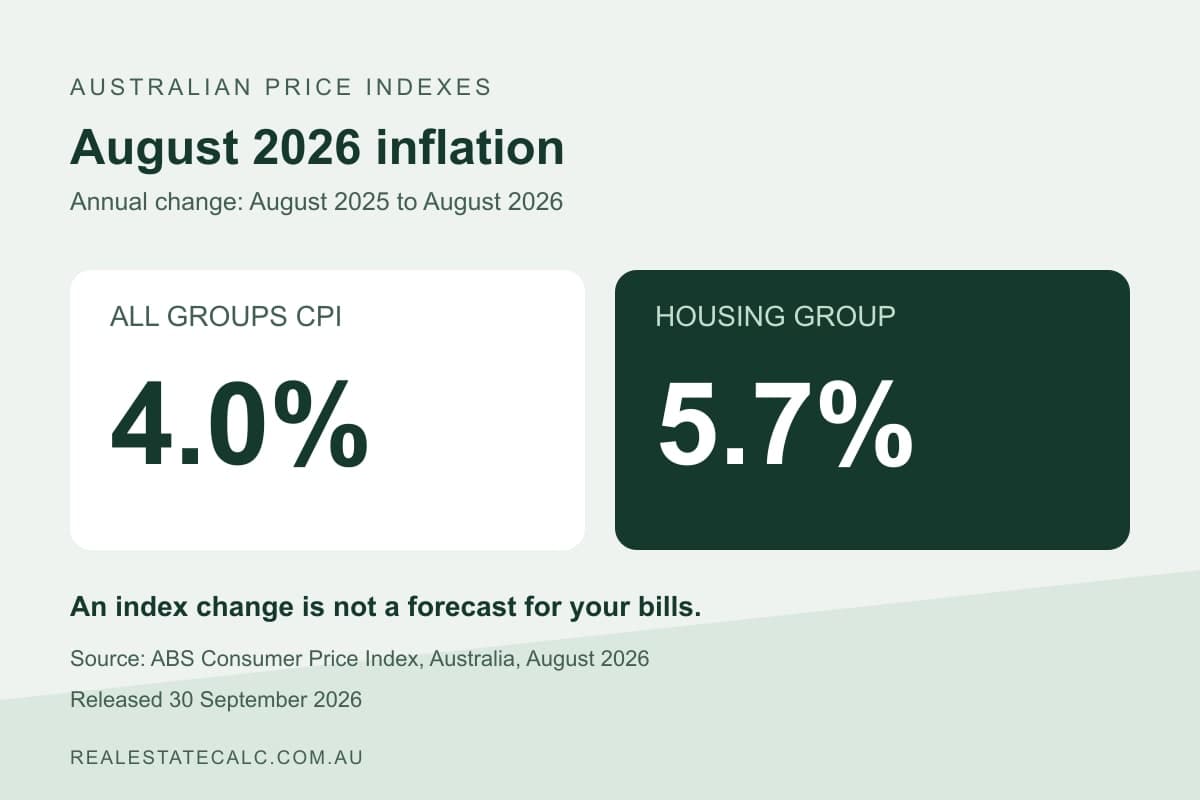
Australian annual CPI inflation increased to 4.0% in August 2026, from 3.5% in July. The ABS released the figures on 30 September 2026. Housing was the largest contributor to the annual result, with prices in that group up 5.7%.
This update matters to households reviewing ownership expenses, but applying 4.0% to every bill would create a scenario, not a forecast. Start with current bills and renewal notices. Use the Inflation Calculator only where an explicitly assumed future rate helps answer the question.
Read the period beside each number
| Measure | August 2026 result | Comparison |
|---|---|---|
| All groups CPI, annual | 4.0% | August 2025 to August 2026 |
| Housing group, annual | 5.7% | August 2025 to August 2026 |
| Trimmed mean, annual | 3.6% | Unchanged from July's annual rate |
| All groups CPI, monthly original | 0.4% | July to August 2026 |
| All groups CPI, monthly seasonally adjusted | 0.7% | July to August 2026 |
Source: ABS August 2026 CPI release. The annual and monthly figures measure different intervals. Do not add them together.
The ABS attributes the housing result to rising new-dwelling and electricity prices. Its media release reports annual new-dwelling price growth of 5.4%. That is context for reading the index, not a quotation for a particular building project.
Worked example: a bill change is different from an index change
Consider an invented household whose annual home insurance renewal rises from $2,000 to $2,300. The dollar increase is $300. Dividing $300 by the original $2,000 gives 15%.
A 4.0% scenario applied to the original premium would instead produce $2,080, an $80 increase. The actual assumed renewal in this example is $220 above that scenario. Neither the $2,300 premium nor its 15% change is an ABS statistic or a typical insurance quote.
For a steady monthly allowance, $2,300 divided by 12 is approximately $191.67. That tells the household how much to allocate over a full year. It does not establish that enough cash will exist when the renewal falls due.
If only four monthly transfers remain before payment and $900 has already been reserved, the unfunded amount is $1,400. Dividing by four gives $350 per transfer. This catch-up figure and the full-year monthly allowance answer different questions. See the annual and quarterly home bills worksheet for the complete method.
Who may need to revisit their estimates?
An owner reviewing a budget can replace an expired insurance estimate with the renewal amount. Someone comparing purchase scenarios can keep ongoing expenses alongside the Property Purchase Cost Calculator, which addresses acquisition costs. A borrower can use the Mortgage Repayment Calculator with their loan's rate and remaining term, then add other expenses separately.
Do not multiply a calculated mortgage repayment by 4.0% and describe the result as a lender's new repayment. A CPI release does not supply a loan rate, contractual repayment or effective date. The September RBA decision article covers the separate cash-rate announcement.
Calculator impact and uncertainty
No formula or government threshold changes follow from this CPI release. The inflation calculator remains a constant-rate scenario tool. The latest annual observation should not silently become a forecast for every future year.
The release cannot determine an individual premium, rent, utility bill or construction quote. It also does not establish the next RBA decision. Keep the reference month visible when comparing this article with the July CPI update.
For the separate question of what the index measures, read whether CPI includes house prices and mortgage interest.
Sources and limitations
- ABS: Consumer Price Index, Australia, August 2026, released 30 September 2026, checked 4 October 2026.
- ABS: CPI rose 4.0% in the year to August 2026, checked 4 October 2026.
- The insurance and cash-timing calculations are original hypothetical examples, not ABS data or quotes.
General information and indicative estimates only. This is not financial, legal, tax or credit advice, an insurance recommendation, a valuation or a forecast. Confirm actual amounts and dates with the relevant provider.
Last updated: 4 October 2026.
Frequently asked questions
Did August 2026 prices rise 4.0% in one month?
No. The 4.0% result is the annual change. The August monthly result was 0.4% in original terms and 0.7% seasonally adjusted.
Should every household bill be increased by the CPI rate?
No. Use current bills, quotes and renewal notices where available. Applying one CPI rate to all costs creates an assumption, not a prediction for each bill.
RealEstateCalc Editorial
Property & Finance ResearchThe RealEstateCalc editorial team researches and writes about Australian property, finance, and tax topics. All content is fact-checked against official sources including the ATO, state revenue offices, ASIC Moneysmart, and the RBA.
Related Calculators

Inflation Calculator Australia
Model how a constant assumed annual inflation rate changes an amount over time. This is a scenario tool, not a historical CPI lookup.
FinanceMortgage Repayment Calculator
Calculate mortgage payments, total interest, and view an amortisation schedule for your home loan.
FinanceProperty Purchase Cost Calculator
Estimate the total upfront costs of buying property in Australia, including stamp duty, government fees, legal costs, inspections, insurance, and moving expenses.
PropertyRelated Articles
Annual and Quarterly Home Bills: Build a Monthly Allowance
Convert annual and quarterly home bills into a monthly allowance, then check cash available before each due date. Includes an Australian dollar worked worksheet.
July Inflation Eased to 3.5%, but Housing Costs Rose 5.0%
Australian annual inflation eased to 3.5% in July 2026 while the ABS housing group rose 5.0%. See the rent, new dwelling and utility detail and what it cannot tell one household.
Does Australian CPI Include House Prices or Mortgage Interest?
Australian CPI includes rents and new owner-occupier dwelling construction excluding land, but not existing house prices or mortgage interest. See which measure fits each question.
Ready to try the Inflation Calculator Australia?
Use the calculator to model an indicative estimate from the assumptions you enter.
What moved in Australian property this week — in your inbox Sunday.
RBA decisions, clearance rates, policy shifts and the calculators that dropped. Two-minute read, no filler.
Free. No spam. Unsubscribe anytime.